


MARKET REVIEW FOREX TREASURIES FED
Yields Surge Past 5.3% as Inflation Fears Roar Back
Services surveys show business costs rising at the fastest pace in nearly four years, while a soft jobs report pushes October Fed hike bets aside and leaves the dollar, gold and oil waiting on Wednesday's FOMC minutes.
Followme News Desk | October 6, 2026
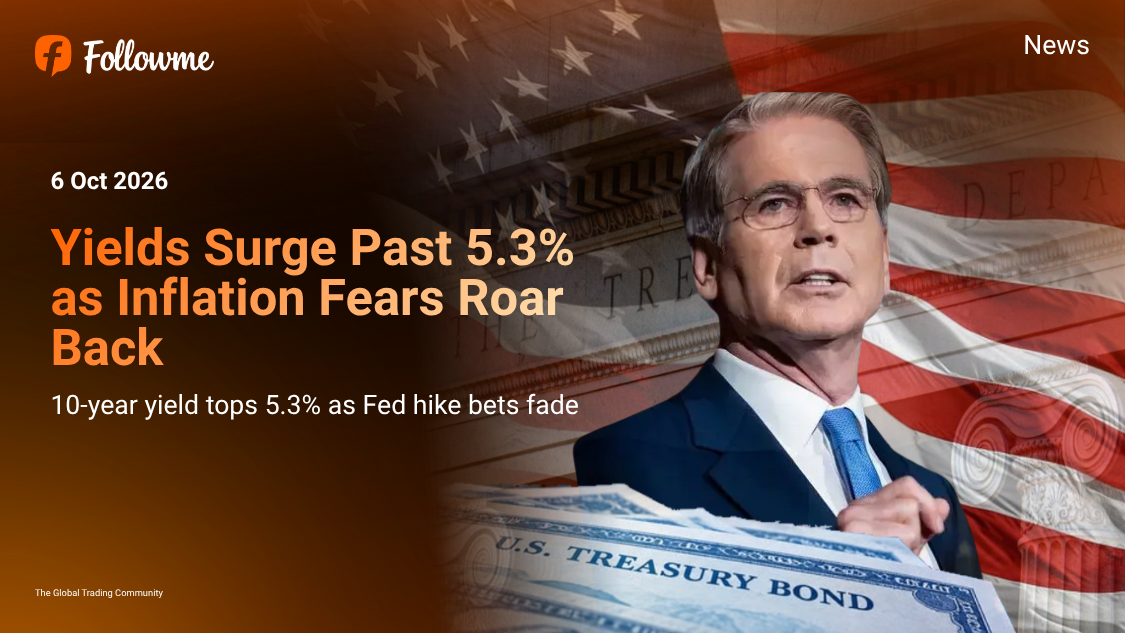
The bond market is setting the tone this week, and it isn't sending a calm message. The US 10-year Treasury yield rose more than 3 basis points to 5.307% on Monday, with the 30-year also hitting a multi-year high. The trigger wasn't a single headline but a build-up of inflation signals that traders had briefly set aside after Friday's weak job numbers. France's budget troubles added fuel, lifting borrowing costs globally.
Monday's ISM Services report was the clearest example. The headline PMI eased to 54.9 from 55.4, a touch below the 55.0 consensus, and the Business Activity Index dropped more than five points to 56.5. On the surface, it looks like a cooling economy. Underneath, the Prices Index climbed to 74.0, its sixth reading above 70 in seven months, and no industry in the survey reported paying less. Fuel costs were cited twice as often as any other supply chain problem, and the employment gauge crept back into expansion for the first time in three months.
S&P Global's services survey, released the same morning, was much stronger. Its Business Activity Index jumped to 58.8 from 56.5, the sharpest expansion since July 2021, with new orders at a four-and-a-half-year high and hiring at its fastest pace since June 2022. Chief Business Economist Chris Williamson said the numbers point to growth of around 4% in the third quarter, but warned that rising selling prices signal inflation staying well above the Fed's 2% target.
That puts the Fed in an uncomfortable spot. Friday's payrolls showed only 29,000 jobs added against expectations near 90,000, with July and August revised down by a combined 60,000. The unemployment rate edged up to 4.2%, though it remains close to a record stretch below 5% last seen in the mid-1960s. First Trust argues the report was not as weak as it looked, noting that household employment rose 406,000 and wage growth of 3.0% year-on-year gives the Fed little reason to rush. Its economists expect any hike to be pushed to December, partly because a move the week before the midterms would look political.
Oil, meanwhile, is pulling in the opposite direction. WTI dropped more than 2% to around $89.29 on Monday after the G7 agreed to release over 100 million barrels of crude and diesel, then slipped further to near $88.35 after President Trump signed an executive order easing restrictions on tax-exempt diesel. Trump said the measure would "allow anyone to purchase tax-free, red-dyed diesel for any reason," his latest step to bring fuel costs down before November's vote.
The dollar remains near its year-to-date high, supported by elevated yields and geopolitical uncertainty, even as October hike bets fade. Gold dipped to about $4,141 after the ISM data and is holding below $4,150.
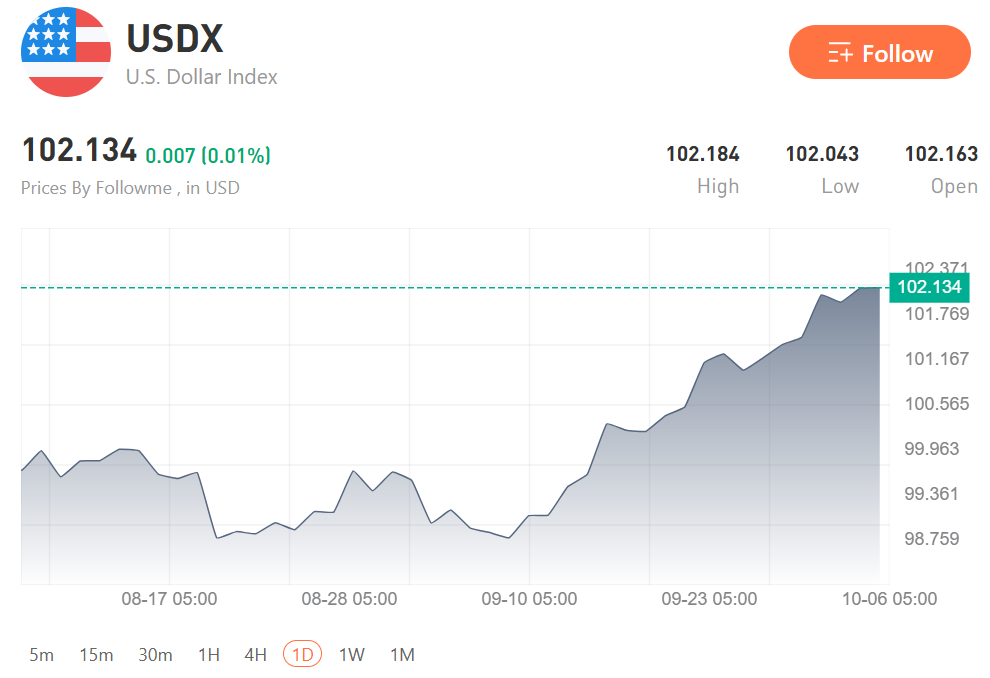
USDX price as of 6 October 2026 - View Live Chart →
The Facts
- Treasury yields: US 10-year yield up more than 3bp to 5.307%; 30-year and 10-year at multi-year highs. France's fiscal crisis is also lifting global yields.
- ISM Services PMI (September): 54.9 vs. 55.4 prior and 55.0 consensus. Business Activity 56.5 (from 61.7), New Orders 59.8, Employment 50.1 (back in expansion), Prices 74.0 (highest since July 2022).
- S&P Global US Services PMI: 58.8 from 56.5, fastest growth since July 2021. Composite PMI at 58.4. Input cost inflation is the steepest since November 2022.
- Labour market: September payrolls +29,000 vs. ~90,000 expected. The unemployment rate is 4.2% from 4.1%. The prior two months revised down by 60,000 combined.
- Fed pricing: Around 76% probability of no change at the October 27-28 FOMC meeting. First Trust sees a December hike as more likely.
- Inflation backdrop: Headline CPI at 3.4%; CPI excluding energy at 2.5%, the lowest since 2021. Average hourly earnings are up 3.0% year-on-year.
- Oil: WTI near $88.35, down over 2%, after the G7 agreed to free more than 100 million barrels of crude and diesel and Trump eased limits on red-dyed diesel.
- Gold: Dipped to around $4,141 after the ISM release; holding below $4,150.
- US debt: Interest costs run near $1 trillion a year on debt above $40 trillion. Apollo's Torsten Slok estimates one in every five tax dollars now goes to servicing the debt.
What It Means
The market is trying to price two economies at once. One shows a cooling labour market and a services sector that's losing a bit of momentum. The other shows companies paying more for almost everything and passing those costs on. Bond traders have clearly decided the second story matters more right now, and that's why yields are rising even as October rate hike bets fall away.
The fiscal angle is adding weight. A Reuters analysis carried by Kitco notes long-term yields are near their highest in two decades, driven by heavy debt issuance, slow-cooling inflation, and an AI investment boom that keeps the economy strong enough to stop rates falling. DoubleLine's Jeffrey Gundlach said the government is becoming uncomfortable with the level of rates. Capital Economics sees the risks tilted toward an inflationary path rather than austerity, which would be bad news for bondholders over time.
For foreign exchange and commodities traders, this matters because yields, not Fed rhetoric, are doing most of the tightening. That supports the dollar against low-yielders, and FXStreet notes USD/JPY is holding just below 158.00 with Japanese intervention risk in the background. The Canadian dollar looks vulnerable near April 2025 lows as oil slides, while the Australian dollar has held up better, with AUD/USD still near 0.70 on expectations of another RBA hike.
Oil is the wildcard. The G7 release and Washington's diesel moves are a deliberate push to lower fuel costs before the midterms. If that works, it takes pressure off the inflation gauges that just jumped. If it doesn't, the fuel complaints running through the ISM report will keep feeding into prices and the Fed will have a harder time waiting until December.
What Traders Should Watch
US 10-year yield: Holding above 5.30% keeps the dollar supported and gold capped. A pullback below 5.20% would suggest the bond selloff is losing steam.
FOMC minutes (Wednesday): Look for how many officials leaned toward a hike and how much weight they put on energy-driven inflation versus softer labour data.
WTI: Now near $88 after the G7 release. A sustained lower movement would ease inflation fears and take some pressure off yields; a rebound would put the ISM price signal back in focus.
Gold: Stuck below $4,150. Fading Fed hike bets help, but a firm dollar and high real yields keep a lid on it.
This week's data: Today's August trade balance and ADP weekly figures, Thursday's initial jobless claims, and Q3 GDP on October 29 ahead of the Fed meeting.
The Bottom Line The data this week is pulling in different directions, but the bond market has picked a side. Prices are rising faster than the Fed would like, the labour market is softening without collapsing, and Washington is working hard to bring fuel costs down before voters head to the polls. Until Wednesday's minutes offer a clearer read on the Fed's thinking, 5.30% on the 10-year is the number that matters most, and oil around $88 is the variable that could tip the balance either way.
Follow us for daily market insights, analysis, and the tools you need to trade with confidence.
Want to stay ahead of major macro developments that move the market? 👉 Follow Followme and check out the Weekly Economic Calendar
October 6, 2026 | This report is for informational purposes only and does not constitute financial advice. © 2026 Followme News
Download Followme Application
Follow us on:


风险提示:本文所述仅代表作者个人观点,不代表 Followme 的官方立场。Followme 不对内容的准确性、完整性或可靠性作出任何保证,对于基于该内容所采取的任何行为,不承担任何责任,除非另有书面明确说明。

-THE END-