
MARKET REVIEW FOREX FED
Fed Minutes Show Nearly Every FOMC Member Backs More Rate Hikes
October minutes, Waller’s call for a half-point move and Kashkari’s view on market pricing push the dollar index to a 19-month high ahead of the December 8–9 meeting.
Followme News Desk | November 19, 2026
Executive Summary
The minutes from the Federal Reserve’s October 27–28 meeting confirmed what traders had started to suspect. Almost every FOMC participant thinks further rate hikes will likely be needed, and a couple said a move bigger than 25 basis points could come up in December if inflation data stay hot. The Fed held the target range at 3.75%–4.00% in October on a 10–2 vote. Governor Lisa Cook and Cleveland Fed President Beth Hammack dissented in favour of an immediate hike.
The next inflation print was not kind. October core CPI rose 0.3% month-on-month for a third straight month, which is the threshold Governor Christopher Waller had set for considering a half-point hike. On Wednesday he said the Fed needs “aggressive action.” Minneapolis Fed President Neel Kashkari added that markets now expect more tightening than officials do.
The dollar index rose 0.2% to 103.78, its highest level since April 2025. Gold fell more than 3% to its lowest in over a year, and WTI dropped 3% to about $83.21 after an unexpected US crude stock build. CME FedWatch shows roughly 95% odds of a 25bp hike on December 9.
Market Review
The Fed’s October minutes left little doubt about where policy is headed. Almost every FOMC participant thinks further rate hikes will likely be needed, and a couple said December could bring a move larger than 25bp if inflation stays hot. The Fed held it at 3.75%–4.00% in October, but Cook and Hammack both dissented in favour of a hike, and a few officials who voted to hold called it a close call.
Inflation data since then has backed the hawks. October core CPI rose 0.3% for a third straight month. That is the level Waller said would justify considering a half-point hike, and on Wednesday he called for “aggressive action.” Kashkari said markets now expect more tightening than officials do, and Barr, Daly and Williams also sounded hawkish. The minutes also raised a newer worry: AI-related debt built on opaque financing, which officials see as a risk to financial stability if returns on AI investment disappoints.
Markets reacted quickly. The dollar index rose 0.2% to 103.78, its highest since April 2025. EUR/USD touched a 19-month low near 1.0978, and GBP/USD slipped to 1.3150. Gold fell more than 3% to its lowest in over a year. WTI dropped about 3% to $83.21 after a surprise 3.38-million-barrel crude build.
With CME FedWatch pricing roughly 95% odds of a 25bp hike on December 9, the question is now how far the Fed goes, not whether it hikes. Every inflation rate between now and December is likely to move markets.
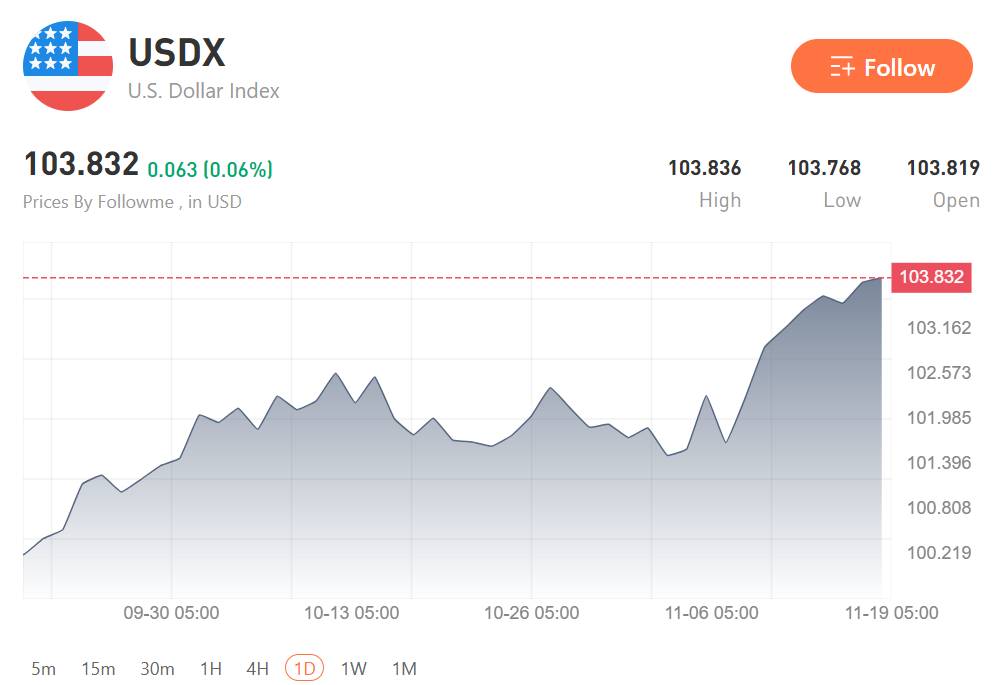
USDX price as of 19 November 2026 - View Live Chart →
The Facts
- Fed decision (October): Held at 3.75%–4.00% on a 10–2 vote. Cook and Hammack dissented in favour of a 25bp hike.
- Minutes: Almost all participants see further hikes as likely appropriate. A couple raised the possibility of a move larger than 25bp in December.
- Inflation: September headline PCE was 3.6% and core PCE 3.1%. October core CPI rose 0.3% m/m for a third straight month.
- Waller: Called for “aggressive action,” meaning either a 50bp hike or a 25bp hike with clear guidance that more are coming.
- Kashkari: Said markets expect more hikes than officials project. He described demand as surprisingly strong and jobs as resilient.
- Rate pricing: CME FedWatch shows about 95% odds of a 25bp hike on December 9, with a small chance of 50bp. Futures imply roughly 75bp of hikes over 12 months, to 4.50%–4.75%.
- NY Fed Desk survey: The median respondent expects hikes in December and March 2027, followed by a cut in early 2028. The median longer-run fed funds estimate rose to about 3.4%.
- USDX: 103.78, a 19-month high.
- Gold: Down more than 3%, its lowest in over a year.
- WTI: About $83.21, down 3% after a surprise 3.38M-barrel crude build.
- Labour market: Unemployment was 4.2% in September, with payrolls averaging about 50,000 a month over three months.
What It Means
A 25bp hike in December is essentially priced in, so the real debate is about how fast and how far the Fed goes after that. The minutes show the committee is more united than the two October dissents suggested. Waller is now openly arguing that a quarter-point move alone could cost the Fed credibility. If the December decision is 25bp with soft guidance, the dollar could give back some of its recent gains. A 50bp hike, or a 25bp hike with an explicitly hawkish statement, would support the case for USDX to push above 104.
Kashkari’s comment matters for positioning. When a Fed official says markets are ahead of the committee, it can mean either of two things. Officials may be catching up to what is priced in, or they may be signalling that markets have gone too far. Wednesday’s broadly hawkish Fed comments point to the first reading for now. That leaves the dollar supported, but it also leaves little room for disappointment if December data cools.
For commodities, the picture is mixed. Higher real rates and a strong dollar are working against gold. Oil is caught between a hawkish Fed and its own supply-and-demand story, and Wednesday’s inventory build showed that the energy premium in inflation can fade quickly. The Fed’s own staff expect energy to drive much of next year’s drop in inflation. If that happens, it gives the doves their best argument for slowing the pace of hikes in 2027.
What Traders Should Watch
USDX at 104.00: The index is at 19-month highs but technically stretched. A clean break above 104.00 opens the way to higher levels. Failure there, even on hawkish headlines, would suggest the December hike is fully priced in.
EUR/USD near 1.0950–1.1000: The pair is testing its April 2025 lows. A sustained close below this area keeps sellers in control.
USD/JPY around 160: The pair is close to levels that have historically drawn warnings from Japanese officials, and a possible BOJ hike in December adds a two-way risk.
November CPI and PCE: These are the last inflation readings before December 9. Another 0.3% core reading would put a 50bp hike seriously on the table.
XAU/USD: The metal is at one-year lows. Any softening in Fed tone or a geopolitical flare-up could trigger a sharp short-covering rally.
WTI around $80: A drop below that level would weaken the energy-driven inflation argument behind the Fed’s hawkish stance.
AI credit headlines: Widening high-yield spreads on data-centre financing are the stability risk the Fed itself has flagged.
The Bottom Line The Fed has made clear that it is not done tightening. What remains open is whether December brings one more quarter-point step or the start of a more forceful push. Until that is settled, the dollar has the advantage, gold is under pressure, and every inflation print from here to December 9 is likely to move markets.
Follow us for daily market insights, analysis, and the tools you need to trade with confidence.
Want to stay ahead of major macro developments that move the market? 👉 Follow Followme and check out the Weekly Economic Calendar
November 19, 2026 | This report is for informational purposes only and does not constitute financial advice. © 2026 Followme News
Download Followme Application
Follow us on:


风险提示:本文所述仅代表作者个人观点,不代表 Followme 的官方立场。Followme 不对内容的准确性、完整性或可靠性作出任何保证,对于基于该内容所采取的任何行为,不承担任何责任,除非另有书面明确说明。
 暂无评论。 来发表第一条观点吧。